Personal Finance Tips for 2026: Build a Money System That Works
Solid personal finance tips are not about restriction. They are about building a repeatable system so your money moves the way you want it to, month after month, without you having to think about every dollar. In 2026, with digital wallets, instant transfers, and automated saving tools everywhere, the people who win with money are not the ones who earn the most. They are the ones who set up a simple structure and then let it run.
This guide walks through the framework I use and recommend: track, categorize, automate, and review. It is practical, US-focused, and built for real life rather than spreadsheets you abandon after two weeks.
Why Do Most Budgets Fail?
Most budgets fail for one boring reason: they demand daily willpower. You start the month motivated, log a few purchases, then miss a day, then a week, then quit. The fix is not more discipline. The fix is design.
A good money system removes decisions. When your savings transfer happens automatically the day after payday, you never have to “decide” to save. When your spending sits on a card you check once a week, you stop the exhausting mental math at every register.
- Automation beats motivation. Set it once, benefit for years.
- Friction is your friend for spending, your enemy for saving. Make saving effortless and impulse buys slightly annoying.
- Simple beats perfect. A rough system you follow crushes a perfect one you ignore.
Step One: Track Before You Cut
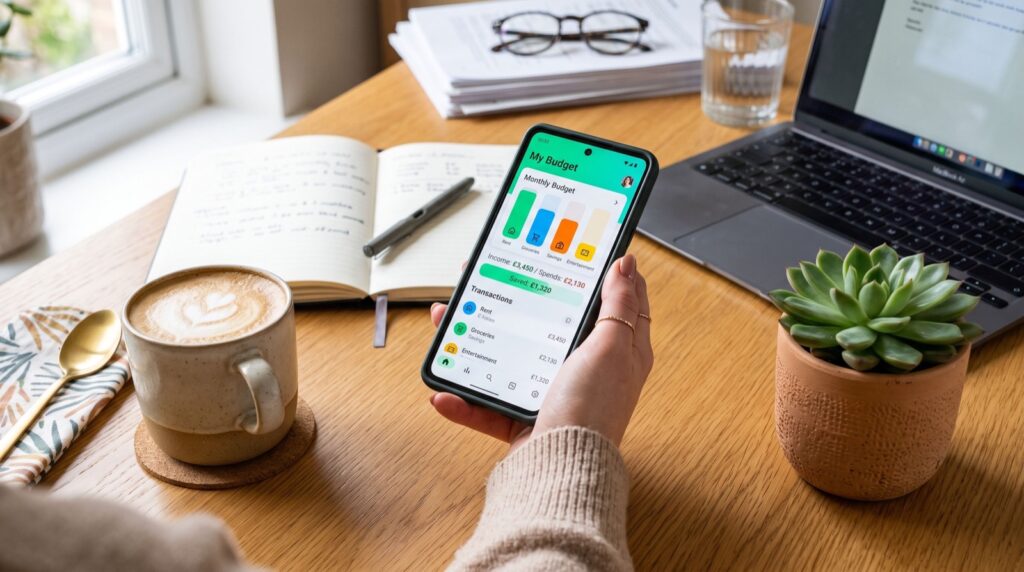
Before you slash anything, you need to know where your money actually goes. Most people are wrong by 20 to 40 percent when they guess their spending. For one month, capture every transaction. You can use a notebook, a spreadsheet, or one of the best money apps that connect to your accounts and categorize purchases automatically.
The goal is awareness, not judgment. Do not change behavior yet. Just watch. By the end of the month you will spot the leaks: the forgotten subscription, the daily coffee that adds up to a car payment, the “small” delivery fees.
Step Two: Use a Percentage Framework
Once you can see your spending, give every dollar a job. A percentage framework is easier to stick to than line-item budgeting because it flexes with your income. The classic 50/30/20 split is a strong starting point, and you can adjust the ratios to fit your reality.
| Bucket | Target % | What Goes Here |
|---|---|---|
| Needs | 50% | Rent, utilities, groceries, insurance, minimum debt payments |
| Wants | 30% | Dining out, streaming, hobbies, travel, upgrades |
| Future | 20% | Emergency fund, retirement, extra debt payoff, investing |
If you live in a high-cost city, your needs may swallow 60 percent. That is fine. Adjust the wants down before you touch the future bucket. Protecting the 20 percent that builds wealth is the whole point.
Step Three: Automate the Boring Parts
This is where the system becomes hands-off. Log into your bank and set up automatic transfers that fire the day after each paycheck lands. Move your future-bucket money out of checking before you can spend it.
- Direct a fixed amount to a high-yield savings account for your emergency fund.
- Max out or steadily fund your retirement account, especially up to any employer match. According to the IRS 401(k) contribution limits, you can shelter a meaningful amount of income each year, and the match is free money you should never leave on the table.
- Schedule extra payments toward your highest-interest debt.
An employer match is often a 100 percent instant return. No investment on earth reliably beats that, so capturing it should come before almost everything except a starter emergency fund.
Step Four: Build the Emergency Fund First
Before aggressive investing or extra debt payoff, park a cushion of cash you can reach fast. Start with $1,000, then build toward three to six months of essential expenses. This fund is what keeps a flat tire or a medical bill from becoming a credit-card spiral.
Keep it in a separate high-yield savings account so it earns interest but stays out of sight. In 2026, online savings rates remain far above what big brick-and-mortar banks pay, so shop around. If you are choosing tools, a solid experienced local team or trusted review site can help you compare account features without the marketing spin.
Step Five: Review Once a Week, Adjust Once a Month
A system still needs a light touch. Spend ten minutes each week glancing at your spending category and your account balances. Once a month, do a slightly deeper check: did any category blow up, did a new subscription sneak in, is your savings rate on track?
This rhythm keeps you connected to your money without the burnout of daily logging. Over a year, those small corrections compound into thousands of dollars.
What About Debt Payoff Strategy?
Two proven methods work: the avalanche (pay highest interest first, saves the most money) and the snowball (pay smallest balance first, builds momentum). The math favors avalanche, but the psychology often favors snowball. Pick the one you will actually finish. A method you follow beats a spreadsheet-perfect plan you quit.
Frequently Asked Questions
What are the most important personal finance tips for beginners?
Start by tracking spending for one month, build a small emergency fund, capture any employer retirement match, and automate your savings transfers. These four moves handle most of the risk and set the foundation for everything else.
How much should I keep in an emergency fund?
Aim for three to six months of essential expenses. If your income is variable or you support a family on one earner, lean toward six months or more. Begin with a $1,000 starter fund and build from there.
Are budgeting apps worth it in 2026?
For most people, yes. Apps remove the friction of manual tracking, auto-categorize spending, and surface trends you would otherwise miss. Choose one with strong security and only the features you will actually use, then let automation do the heavy lifting.
Should I pay off debt or invest first?
Capture any employer match first, then build a starter emergency fund, then attack high-interest debt (above roughly 7 to 8 percent) before investing beyond the match. Low-interest debt can often run alongside investing.
Your Next Move
The best time to build a money system was years ago. The second-best time is this week. Pick one action from this guide, tracking, automating, or opening a high-yield account, and do it today. Layer the rest in over the next month. These personal finance tips only work when you act on them, and the compounding starts the moment you begin. Small, automated, consistent moves are how ordinary incomes turn into real financial security by 2026 and beyond.